How Should a Scottsdale or Mesa Cannabis Dispensary or CBD Retailer Set Up Payment Processing?
If you run a cannabis dispensary or CBD shop in Scottsdale, Mesa, or anywhere across the Phoenix metro, you already know that payment processing is one of the most frustrating parts of the business. Most major processors won’t touch you. The ones that will often come with sky-high fees, vague contract terms, or accounts that get shut down without warning. The good news is that real solutions exist — you just need to know what they are, what the risks look like, and how to protect your business from account terminations and compliance headaches.
Let’s cut through the noise and talk about what actually works.
Why Cannabis and CBD Businesses Are Classified as High-Risk
At the federal level, cannabis is still a Schedule I controlled substance — which means most banks and card networks (Visa, Mastercard) won’t knowingly process card transactions for cannabis dispensaries. Even hemp-derived CBD, which was federally legalized under the 2018 Farm Bill, gets flagged by many processors because the product category sits close enough to cannabis that underwriters treat it cautiously.
For dispensaries specifically, this creates a situation where cash becomes the default — and operating a high-volume cash business creates its own problems: security risks, reconciliation headaches, and a worse customer experience for everyone. It’s one of the most underserved pain points for Arizona retail businesses, and it’s a topic that most local processors either gloss over or avoid entirely.
CBD retailers face a slightly different challenge. If your store focuses on hemp-derived, non-THC products — tinctures, topicals, edibles — you may qualify for a standard or high-risk merchant account depending on how your product catalog is described, who your processor is, and how your business is categorized at the MCC (merchant category code) level. The details matter a lot here.
Payment Options That Cannabis Dispensaries in Scottsdale and Mesa Actually Use
Let’s be straight about what’s available right now for licensed dispensaries in Arizona:
- ATM or cashless ATM systems: These are the most common workaround. A customer uses a debit card at a PIN pad, withdraws a rounded dollar amount, and receives change in the form of store credit or cash. These systems are technically running a cash withdrawal, not a card sale. They’re widely used, but they exist in a legal gray area and card networks have increasingly cracked down on them. If you’re using one now, you should know the risk of abrupt termination.
- ACH / bank-to-bank payments: Some dispensaries are moving toward ACH-based payment systems that pull directly from a customer’s bank account. These avoid the card networks entirely and are generally more compliant. They require customers to have a linked bank account and some friction at checkout, but they’re a legitimate, stable option for the right customer base.
- Cash discount programs: If you’re operating a smoke shop or hemp/CBD retail store — not a licensed cannabis dispensary — a cash discount or surcharge program can be a smart way to keep card processing costs low while staying fully compliant with card network rules. Rather than absorbing the processing fee, you post a standard price and offer a discount to customers who pay cash. It’s legal, transparent, and used by retail businesses across the Phoenix metro.
- High-risk merchant accounts (CBD retailers): If you sell hemp-derived CBD products and your MCC is coded correctly, you may qualify for a legitimate high-risk merchant account that allows standard card processing. Rates will be higher than a typical retail account — expect that — but your account is stable and you’re not operating in a gray area.
The Biggest Mistake Dispensary and CBD Owners Make
The most common mistake we see from cannabis and CBD business owners across Maricopa County is signing up with a processor that promises card processing without being upfront about how their system is set up. You get a terminal, things work fine for two or three months — and then the account gets terminated with no warning and potentially a hold on your funds.
That’s not a hypothetical. It happens regularly. And when you’re running a high-volume retail location in Scottsdale or Mesa, a sudden account freeze is a serious business disruption.
The questions you need to ask any processor before signing anything:
- What is my exact MCC code, and who is the acquiring bank?
- Is this processing going through Visa/Mastercard card networks, or is it an ACH-based or cashless ATM system?
- What happens to my funds if the account is terminated?
- Is there a reserve requirement, and how long are funds held?
- Are there any long-term contract terms or early termination fees?
If a processor can’t answer those questions clearly, walk away.
What CBD Retailers in Tempe and Chandler Should Know About Merchant Accounts
Pure hemp-derived CBD retailers have more options than dispensaries, but you still need to work with a processor that understands your product category. If you’re running a smoke shop, hemp store, or CBD wellness boutique in Tempe, Chandler, or anywhere in the East Valley, here’s what a solid setup typically includes:
- A high-risk merchant account with a processor that has specific experience with CBD and hemp retail — not a generic national processor that approved you without knowing what you sell
- A POS system that handles inventory, employee access, and sales reporting without restricting what product types you can ring up
- A cash discount or surcharge program to offset the higher processing rates that come with high-risk accounts
- Clear chargeback monitoring — high-risk accounts often have lower chargeback thresholds before the processor intervenes
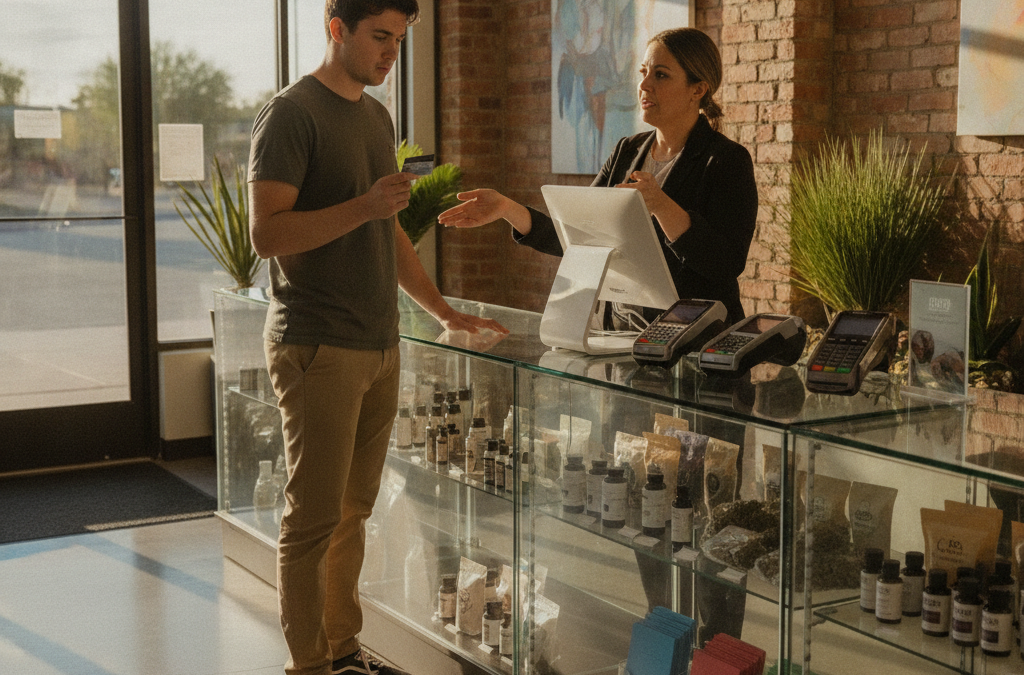
For the POS side of things, Clover is one of the more flexible options for specialty retail because of its open App Market and the ability to customize it to your inventory and workflow. The Clover Mini or Clover Station works well for a retail counter environment, and the Clover Flex gives you mobility if your layout or staffing setup requires it.
What Most Local Processors Won’t Tell You About High-Risk Accounts
Here’s something that tends to get left out of competitor websites and sales pitches: not every high-risk merchant account is the same. The difference between a well-structured account and a poorly underwritten one can mean the difference between stable monthly processing and a frozen account six months in.
At Good Payments, we work with merchants across Scottsdale and the broader Phoenix metro on high-risk category setups — including CBD retailers and smoke shops — with a focus on transparency about what you’re actually signing up for. No long-term contracts. No bait-and-switch pricing. And if something doesn’t fit, we’ll tell you that upfront instead of taking your business and hoping you don’t notice the fine print.
If you’re a Phoenix or Scottsdale area business owner in a high-risk category and you’ve been burned before by an account termination or unexpected fees, a free rate analysis is a good first step to understanding what your actual options look like.
Frequently Asked Questions
Can a licensed cannabis dispensary in Arizona accept credit cards?
Not through standard Visa or Mastercard card networks. Most dispensaries use cashless ATM systems (which exist in a gray area), ACH-based payment platforms, or cash-only operations. The legal and compliance landscape is shifting, but as of now, true card processing for cannabis remains off-limits through traditional channels.
Can a CBD retailer in Scottsdale or Mesa get a merchant account?
Yes — if your products are hemp-derived and contain less than 0.3% THC, you can typically get approved for a high-risk merchant account. The key is working with a processor that understands the product category and codes your account correctly from the start.
What’s a cashless ATM, and is it legal?
A cashless ATM is a PIN pad that processes transactions as cash withdrawals rather than card purchases, allowing dispensaries to accept debit cards. It’s widely used but operates in a compliance gray area — card networks have been cracking down on these systems, and accounts can be terminated without notice. It’s a short-term workaround, not a long-term solution.
Will a cash discount program work for a smoke shop or hemp store in Phoenix?
Yes. A properly structured cash discount program is fully compliant with card network rules and is a common way for high-risk retailers to offset processing costs. You post your standard price, offer a discount to cash-paying customers, and card-paying customers cover the processing fee. It’s straightforward and legal when set up correctly.
What should I look for in a processor if I run a high-risk retail business in the East Valley?
Look for a processor who can clearly explain your MCC code, name the acquiring bank, spell out any reserve requirements, and offer month-to-month terms. Avoid anyone who can’t or won’t answer those questions. Local processors who work specifically with Arizona businesses in your category are generally better equipped to support you than a national call-center processor who approved you without really vetting what you sell.
Ready to Talk Through Your Options?
If you run a dispensary, CBD shop, smoke shop, or any high-risk retail business in Scottsdale, Mesa, Phoenix, Tempe, or Chandler, you deserve a straight answer about what’s actually available to you — not a pitch that leaves out the important details. At Good Payments Merchant Services, we work with business owners across the Valley who’ve been burned before and want to get it right this time.
Reach out for a free consultation and rate analysis. We’ll look at your current setup, tell you exactly what we see, and give you honest options — no pressure, no long-term commitment required to have the conversation.